Beijing Draws the Line: How China's New Productive Forces Guidelines Aim to Prevent an AI Bubble

*The Great Wall — a fitting metaphor for how Beijing approaches industrial policy: massive in scale, deliberate in construction, designed for the long term. On October 9, 2026, China's leadership added a new layer of governance to its AI ambitions. (Image: Unsplash)*
On October 9, 2026, the Chinese government released a set of guidelines for developing "new quality productive forces" — the policy framework that has become the centerpiece of Beijing's economic strategy. The document was remarkable not for what it promised to build, but for what it promised to prevent. Alongside pledges to accelerate AI breakthroughs and deploy intelligent systems across every major industry, the guidelines carried an unmistakable warning: no bubbles, no blind investment, no abuse of industrial policy in the name of innovation.
The timing is not accidental. China's core AI industry surged past 1.2 trillion yuan ($174 billion) in 2025, growing 40% year over year. More than 6,600 AI companies now operate in the country. Over 400 humanoid robot products have been launched. And the models-and-frameworks segment of the industry grew a staggering 189% in a single year. These are the kinds of numbers that make industrial planners euphoric — and economists nervous.
To understand why Beijing is simultaneously championing and constraining its AI boom, you need to trace the arc of a policy idea that began three years ago and has now evolved into the most consequential technology governance framework in China's history.
The Present Moment: A Policy at the Peak of the Boom
The October 9 guidelines were issued at what might be the precise apex of China's AI investment cycle. The numbers tell a story of extraordinary momentum — and the early signs of the exact excesses the guidelines are designed to prevent.
| Indicator | 2025 Figure | 2026 Mid-Year Figure | Growth Rate |
|---|---|---|---|
| Core AI Industry Scale | ¥1.2 trillion ($174B) | ¥1.7 trillion projected (~$240B) | +40% YoY |
| AI Enterprise Count | 6,200+ | 6,600+ | +6% in 6 months |
| Humanoid Robot Products | 300+ | 400+ | +33% in 6 months |
| Models & Frameworks Segment | ¥84 billion (7% of chain) | Growing at 189% annually | +189% YoY |
| AI Patent Share (Global) | 60% | — | #1 worldwide |
| Open-Source Model Downloads (Cumulative) | 10 billion+ | — | 41% of global total |
| Intelligent Computing Capacity | 1,590 EFLOPS | 42 clusters of 10,000+ GPUs | Expanding |
| New Registered Generative AI Services (2025) | 446 new (748 total) | — | Regulatory pipeline |
*Sources: MIIT, CAICT, National Data Administration, Xinhua*
The growth is real, the technology is transformative, and the strategic importance is undeniable. But so is the risk. China's own economic history — from steel to solar to real estate — demonstrates what happens when local governments, state banks, and private capital all pile into the same sector simultaneously. Capacity overshoots demand by multiples. Prices collapse. Companies that should have failed are kept alive by political pressure and cheap credit. The result is a zombie industry that drags on growth for a decade.
The October guidelines explicitly reference this history. The document vows to "strictly prohibit the illegal or improper abuse of policies in the name of developing new productive forces" — a pointed reference to the practice of local officials using AI and "new economy" labels to justify pet projects, land development schemes, and subsidy grabs that have nothing to do with genuine innovation.
But to appreciate the weight of this intervention, you need to understand where the "new productive forces" concept came from and how it became the organizing principle of Chinese economic policy.
Phase 1: Origins — A Concept Is Born (2023–2024)
The term "new quality productive forces" (新质生产力) entered the official lexicon in September 2023, during a visit by President Xi Jinping to Heilongjiang province. Xi used the phrase to describe a new model of economic growth driven by technological innovation, digitalization, and green energy — explicitly contrasting it with the debt-fueled infrastructure investment and real estate development that had powered China's growth for three decades but had run out of road.
The concept was formally elevated at the Central Economic Work Conference in December 2023 and received its theoretical foundation in a February 2024 study session of the Politburo. The core argument: China's old growth model — low-cost manufacturing, property development, and infrastructure — had hit diminishing returns. The new model would be built on breakthrough technologies: artificial intelligence, quantum computing, biotechnology, commercial space, and advanced manufacturing.
AI was always the centerpiece. And the initial policy response was predictable: massive state support, local government AI industrial parks, and generous subsidies for anything labeled "intelligent." By mid-2024, more than 20 provincial governments had published AI development plans. Cities competed to brand themselves as "AI capitals." Investment funds sprouted like bamboo after rain.
The energy was genuine, but so were the warning signs. By early 2025, Chinese economists were quietly noting that the pattern rhymed with earlier boom-bust cycles. Local governments were building AI compute centers that would sit partially idle. Universities were launching AI departments they didn't have faculty to staff. Companies were rebranding existing products as "AI-powered" to qualify for subsidies.
Phase 2: Inflection — The AI Plus Action Plan (2025)
The first serious attempt to impose discipline on the chaos came in mid-2025. In July, the State Council reviewed and approved the "Artificial Intelligence Plus" (AI+) Action Plan — a comprehensive framework designed to integrate AI across manufacturing, services, agriculture, and governance.
The AI+ plan was significant not just for what it promoted, but for the governance architecture it began to construct. It introduced the requirement that all generative AI services undergo registration and filing with the Cyberspace Administration of China (CAC). By the end of 2025, 748 AI services had been registered — a pipeline that gave regulators visibility into who was building what, and at what scale.
| Regulatory Milestone | Date | Impact |
|---|---|---|
| First AI Management Regulation | July 2023 | Mandated legally sourced data and models; prohibited infringement of legitimate rights |
| Generative AI Filing System Launched | August 2023 | Began regulatory pipeline for AI services |
| AI+ Action Plan Approved | July 2025 | Integrated AI into national industrial strategy |
| Revised Cybersecurity Law | October 2025 (effective Jan 1, 2026) | Added AI ethics rules, risk monitoring, safety oversight |
| Anthropomorphic AI Draft Rules | Late 2025 | Regulated AI interaction services; penalized AI mimicking public figures |
| 15th Five-Year Plan Recommendations | October 2025 | Positioned AI as key driver of industrial upgrading |
| New Productive Forces Guidelines | October 9, 2026 | Comprehensive framework: acceleration + bubble prevention |
The revised Cybersecurity Law, which took effect on January 1, 2026, added another layer. It required AI applications to undergo risk assessments, mandated that AI systems be "controllable" by human operators, and gave regulators the authority to shut down AI services that posed threats to "national security, public safety, or individual rights."
These were the building blocks. The October 2026 guidelines assembled them into a coherent structure — and added the piece that had been missing: a systematic approach to preventing the financial and industrial excesses that could destroy the very productivity gains the technology promised.
Phase 3: Acceleration — The Boom Beijing Wants to Tame
Between the AI+ plan's approval in July 2025 and the October 2026 guidelines, China's AI industry experienced one of the most explosive growth phases in the history of the technology. Understanding this acceleration is essential to understanding why the guidelines matter — and why they're so difficult to implement.
The numbers are staggering across every dimension:
| Segment | 2025 Share of AI Industry | Growth Rate | Key Dynamics |
|---|---|---|---|
| Applications | 55% | +22% YoY | Manufacturing AI adoption >30%; 4.11B internet medical users served |
| Foundational Infrastructure | 38% | +59% YoY | 1,590 EFLOPS compute; data center REITs emerging |
| Models & Frameworks | 7% | +189% YoY | Explosive startup formation; token price wars; open-source proliferation |
| AI Investment Fund (State) | ¥60 billion fund size | Deploying since 2025 | Focus on commercialization and deployment capability |
The models segment's 189% growth rate deserves attention. This is where the bubble risk concentrates. Chinese AI model companies attracted enormous venture capital inflows during 2025 and 2026, driving valuations often disconnected from revenue. The API token price wars — which saw DeepSeek, Alibaba, ByteDance, and others slash inference costs by 70-90% — demonstrated both Chinese engineering efficiency and the unsustainable unit economics of a market where every major player was subsidizing usage to capture share.
Meanwhile, the compute infrastructure buildout raised its own concerns. China's intelligent computing capacity reached 1,590 EFLOPS, with 42 clusters of 10,000 or more GPUs. That infrastructure is strategic — but if model efficiency continues to improve at the rate DeepSeek V4.1 Flash demonstrated (fitting frontier performance into a quarter of the GPU memory), some of that capacity could face the same underutilization that plagued China's solar factories.
The parallel with solar is instructive. By the end of 2025, China had built 1,100 GW of solar module manufacturing capacity against a domestic installation forecast of 180-240 GW for 2026 — a capacity utilization rate below 25%. The China Solar Overcapacity Index read 64.1 in H1 2026, meaning nearly two-thirds of factory lines sat idle. The government responded by capping steel industry growth at 4% and pushing "anti-involution" policies to force consolidation.

*China's solar industry built 1,100 GW of module capacity against ~200 GW of domestic demand — the overcapacity scenario the new AI guidelines explicitly seek to prevent. (Image: Unsplash)*
The AI guidelines are, in large part, an attempt to prevent the AI industry from following the same trajectory.
Phase 4: The Guidelines — What They Actually Say
The October 9 document addresses every layer of the AI stack — from basic research to commercial deployment — and establishes governance mechanisms for every stakeholder. The acceleration agenda includes AI theory breakthroughs, compute and data supply strengthening, full AI+ deployment across industries, smart terminal ecosystem expansion, and international open-source cooperation.
But the defensive provisions are where the guidelines break new ground:
- Technology monitoring systems — real-time surveillance of AI behavior at scale
- Risk warning mechanisms — early detection of safety incidents and systemic vulnerabilities
- Emergency response protocols — pre-defined procedures for AI failures
- Strict prohibition on policy abuse — preventing local government misuse of AI designations
- Bubble prevention — financial regulator monitoring of AI-sector valuations
- Anti-overcapacity measures — compute investment coordination to prevent the solar scenario
The safety architecture integrates three layers into China's existing regulatory framework:
| Layer | Mechanism | Responsible Body | Enforcement Power |
|---|---|---|---|
| Pre-Deployment | Model filing and registration; algorithm review; data provenance audit | CAC, MIIT | Can block deployment |
| In-Operation | Technology monitoring; risk warning systems; usage pattern surveillance | CAC + industry regulators | Can mandate modifications; suspend services |
| Post-Incident | Emergency response; investigation; penalties; public disclosure | State Council + CAC | Shutdown authority; criminal referral |
This is more comprehensive than any AI governance framework in existence. The EU's AI Act, which took effect in August 2026, is risk-tiered but doesn't include real-time monitoring. The US approach remains fragmented across executive orders, agency guidelines, and state-level legislation. China's framework — building on three years of iterative regulation — now covers the full lifecycle from model conception to operational surveillance to incident response.
The Global Context: Why This Matters Beyond China
The guidelines arrive at a moment when the global AI industry is gripped by a fundamental question: is the current investment boom sustainable? The numbers from the United States suggest cause for concern.
American hyperscalers — Alphabet, Microsoft, Amazon, Meta, and Oracle — are projected to spend over $750 billion on data centers in 2026, with total AI capital investment potentially exceeding $5 trillion over the next four years. Yet total AI revenues are estimated at only $150-200 billion this year. Alphabet reported its first free cash flow deficit since its 2004 IPO. Morgan Stanley calculates that more than half of the $2.9 trillion in AI infrastructure spending between 2025 and 2028 will be financed with external capital, meaning debt — a structure that distributes risk throughout the financial system in ways that are "invisible" to most investors, in the words of Columbia Business School professor Stijn Van Nieuwerburgh.
The contrast with China's approach is instructive:
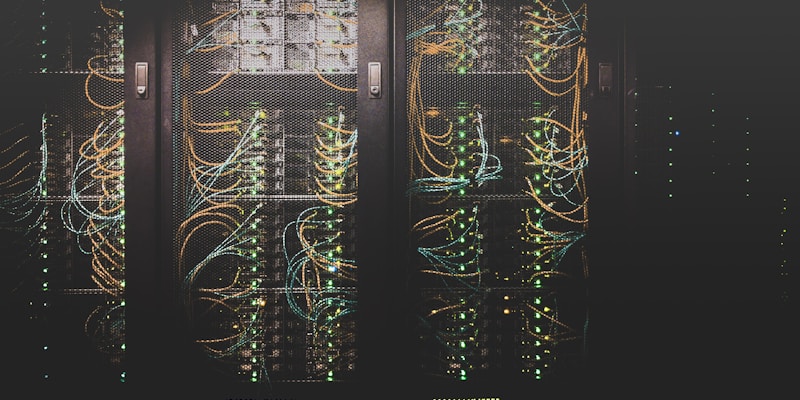
*Global data center capex surpassed $700 billion in 2025 and is crossing $1 trillion in 2026 — but revenues remain a fraction of that spend. China's guidelines attempt to close the investment-revenue gap before it opens. (Image: Unsplash)*
| Dimension | United States | China (Post-Guidelines) |
|---|---|---|
| Investment Driver | Corporate capex + private capital | State-directed + corporate + VC |
| Total 2026 AI Spend | ~$660B (hyperscalers) | ~$240B (estimated, all sources) |
| Revenue vs. Spend Gap | $150-200B revenue vs. $750B spend | Smaller absolute gap; deployment-first model |
| Debt Financing | >50% externally financed | Primarily state funds and corporate balance sheets |
| Regulatory Approach | Fragmented, post-hoc | Integrated, lifecycle-based |
| Bubble Prevention | Market-driven (Fed monitoring) | Explicit government mandate |
| Safety Framework | Voluntary commitments + executive orders | Mandatory filing, monitoring, response |
China's model isn't necessarily better — state-directed investment has its own misallocation track record, as solar and steel demonstrate. But the guidelines represent a fundamentally different bet: that AI's value lies in deployment and productivity gains across the real economy, not in financial returns from infrastructure spending. The guidelines explicitly prioritize manufacturing adoption over speculative model development and sustainable unit economics over growth-at-all-costs.
The China Daily editorial that preceded the guidelines — published in June 2026 — articulated this philosophy clearly: "AI should be protected from the speculative dynamics that plagued the real estate sector." The article proposed four guardrails: rigorous verification of AI-related assets, limits on concentration of core AI resources, regular stress testing of AI-related financial products, and suitability requirements for AI-focused investment products. The October guidelines formalize all four.
The Implementation Challenge
The guidelines are ambitious. Executing them will be extraordinarily difficult.
The core tension is between acceleration and containment — and Chinese industrial policy has historically been much better at the former than the latter. Local governments have strong incentives to attract AI companies, build compute centers, and claim "new productive forces" achievements. State banks face political pressure to lend to strategic sectors. And the AI industry itself — with 6,600+ companies competing for talent, capital, and government contracts — will resist anything that slows growth.
The guidelines acknowledge these dynamics. The prohibition on "improper abuse of policies" specifically targets the practice of local officials using AI designations to justify pet projects, land development schemes, and subsidy grabs unrelated to genuine innovation. But prohibiting abuse and preventing it are different things.
The financial bubble risk is equally challenging. Chinese venture capital has already poured enormous sums into AI model companies, and the secondary market for AI-related stocks has been volatile. The guidelines instruct financial regulators to monitor speculative excess — but in a system where the state is simultaneously the largest investor, largest customer, and primary regulator, conflicts of interest are structural.
Perhaps the most difficult challenge is the real-time monitoring system. Building technology to monitor AI systems at national scale — across thousands of deployed models and millions of endpoints — is itself an enormous technical undertaking. And it raises the meta-question: who monitors the monitors?
What's Next: Milestones to Watch
The guidelines set in motion several processes that will unfold over the coming months and years. Here are the key milestones:
| Timeline | Expected Development | What to Watch |
|---|---|---|
| Q4 2026 | Implementation rules from MIIT, CAC, NDRC | Specific thresholds for "bubble" definitions; compute coordination mechanism |
| Q1 2027 | First round of AI-sector financial stress tests | Which companies/sectors are examined; findings on valuation excess |
| Q1 2027 | Local government compliance reviews | How many AI park projects are cancelled or redirected |
| H1 2027 | Real-time AI monitoring system pilot | Scope of initial deployment; technical architecture |
| 2027 | 15th Five-Year Plan mid-course review | Whether AI targets are adjusted based on bubble assessment |
| Ongoing | Generative AI filing pipeline growth | Whether registration pace slows (market cooling) or accelerates (continued boom) |
The most telling indicator will be what happens to the models-and-frameworks segment — the 189%-growth corner of the industry where bubble risk is highest. If the guidelines successfully redirect capital from speculative model development toward applied deployment and manufacturing integration, the growth rate should moderate. If it continues at triple digits, the containment architecture will have failed.
Social Voices
Reactions across Chinese social media and international platforms reflect the complexity of the moment — hope, skepticism, and hard-headed analysis coexist:
@量子位观察者 on Zhihu:
"国家终于出手了。AI行业的钱太多了,但真正的落地应用还不够多。这不是泼冷水,是让行业走得更稳。" *"The state has finally stepped in. There's too much money in AI, but not enough real deployment. This isn't throwing cold water on the industry — it's making the industry walk more steadily."*
@TechPolicyAnalyst on X (Twitter):
"China's AI guidelines are the most comprehensive attempt yet to prevent an AI bubble. The US is spending $750B/year with $150B in revenue. China is trying to avoid that math. Whether it works depends on local government compliance — which is the eternal weak link."
>
@深水静流1995 on Xiaohongshu:
"看了文件全文,感觉重点不是限制AI发展,而是防止地方政府借着AI的名义乱投资。太阳能和房地产的教训太深刻了。" *"After reading the full document, the focus doesn't seem to be restricting AI development but preventing local governments from making reckless investments in AI's name. The lessons from solar and real estate are too painful."*
@DataDrivenDan on Hacker News:
"The monitoring system is the part that should concern everyone. Real-time surveillance of AI systems at national scale is technically impressive and ethically fraught. China is building the infrastructure for something no other country has attempted — for better or worse."
>
@AI政策研究员 on Weibo:
"'新质生产力'这个框架终于有实施细则了。关键看执行——文件写得再好,如果地方政府为了GDP继续盲目上项目,一切都是空谈。" *"The 'new productive forces' framework finally has implementation details. The key is execution — no matter how well the document is written, if local governments continue launching blind projects for GDP growth, it's all empty talk."*
@Sinosecurity on X (Twitter):
"Everyone's focused on the bubble prevention angle, but the AI safety monitoring system is the bigger story. China is building a national AI incident detection and response infrastructure. When the first major AI safety event happens globally, Beijing will be the best-prepared government to respond — and that has geopolitical implications."
The Bottom Line
The October 9 guidelines represent a maturation of China's AI strategy — from enthusiastic boosterism to disciplined statecraft. The "new productive forces" concept that began as a theoretical construct in 2023 has evolved into a comprehensive governance framework that attempts something no other country has tried: capturing the productivity gains of AI while preventing the financial and industrial pathologies that have accompanied every previous technology boom in Chinese economic history.
The ambition is undeniable. The architecture is more sophisticated than anything in the US or EU. The intent is clear. But the execution risk is equally clear. China's central government has a long history of issuing well-crafted policies that run aground on the shoals of local implementation, vested interests, and the sheer difficulty of managing an economy of 1.4 billion people.
What the guidelines make unambiguous is that Beijing has studied America's AI boom — with its trillion-dollar data center buildout, its debt-fueled capex, its gap between investment and revenue — and decided not to replicate it. Whether that decision is prescient or counterproductive will define not just China's AI trajectory, but the global shape of the most important technology of the 21st century.
The world is about to find out if you can have an AI revolution without an AI bubble. Beijing has placed its bet.
*Related articles:*
- The Day Nvidia Wrote Down China: How Beijing Built a Chip Empire Out of Sanctions
- The Model Nobody Freaked Out About: DeepSeek V4.1 Flash and the Quiet Disruption of AI Economics
- China's AI Compute Empire: How Sanctions Became a Boomerang
Editor at AI in China. Tracking Chinese AI companies, funding rounds, and the technologies reshaping global tech. More about me.